
Prepare e-file IRS 1099 NEC, MISC, INT, DIV, R, A & K for 2026 Tax year File 1099 Forms Online
File IRS Form 1099-A Online for 2026-27
Prepare and e-file IRS Form 1099-A for calendar year 2026 with Form1099Online. Lenders, businesses, and other eligible filers can use the online filing service to prepare information returns for qualifying acquisitions or abandonments of secured property.
Form1099Online provides an online option for preparing Form 1099-A and submitting it electronically.
Before filing, review the loan records, borrower information, property details, and applicable IRS reporting requirements. Form 1099-A is generally filed in the year following the calendar year in which the lender acquires an interest in the secured property or knows, or has reason to know, that the property has been abandoned.
- Online filing: Prepare Form 1099-A using the online filing platform.
- Convenient preparation: Enter lender, borrower, debt, and property information online.
- No sign-up fee: Create an account without an initial registration fee. Review the current filing charges before submission.
What Is IRS Form 1099-A?
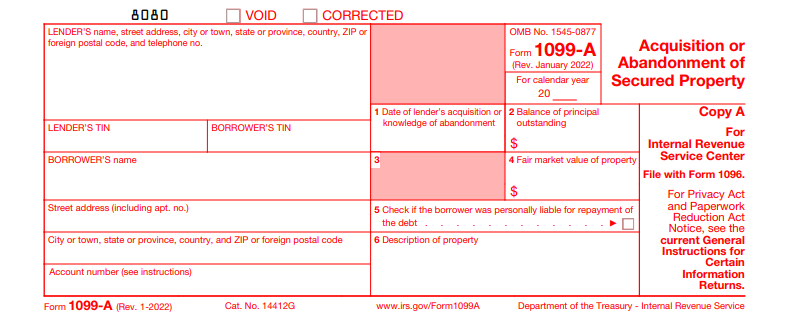
IRS Form 1099-A, Acquisition or Abandonment of Secured Property, is an information return used to report certain events involving property that secures a debt.
A lender generally files Form 1099-A when it lends money in connection with its trade or business and, in full or partial satisfaction of the debt, acquires an interest in the secured property or has reason to know that the borrower has abandoned the property.
The reporting requirement is not limited to businesses whose primary activity is lending money. Certain other businesses and organizations may also have filing obligations when the applicable IRS conditions are met.
The form reports information such as the date of acquisition or knowledge of abandonment, outstanding principal balance, fair market value of the property, and whether the borrower was personally liable for the debt.
Form 1099-A is different from Form 1099-C, Cancellation of Debt. Although the forms address different reporting requirements, a qualifying foreclosure or abandonment and debt cancellation may be reported under the coordination rules for these forms.
Who Needs to File Form 1099-A?
Businesses and other lenders may need to file Form 1099-A when a qualifying acquisition or abandonment of secured property occurs.
Common filing situations include:
- Business lenders: Businesses that lend money and acquire an interest in secured property or have reason to know that the property has been abandoned.
- Governmental units: Government agencies and qualifying subsidiary agencies that lend money secured by property.
- Multiple loan owners: Trustees, record owners, or persons acting in a similar capacity who report on behalf of multiple owners of interests in a loan.
- Subsequent loan holders: New holders of a loan who become responsible for reporting qualifying events occurring after the transfer.
- Multiple lenders: Lenders whose security interests are affected when another lender forecloses or acquires an interest in the property.
The reporting obligation depends on the nature of the loan, the secured property, the event, and the applicable IRS rules.
What Information Is Required for Form 1099-A?
Before preparing Form 1099-A, collect the lender’s identifying information, the borrower’s details, and the relevant loan and property records.
The form includes the following information:
| Form field | Information required |
|---|---|
| Lender’s information | Lender’s legal name, address, telephone number, and taxpayer identification number (TIN) |
| Borrower’s information | Borrower’s name, address, and TIN |
| Box 1 | Date of the lender’s acquisition or knowledge of abandonment |
| Box 2 | Outstanding principal balance of the debt |
| Box 4 | Fair market value (FMV) of the property, when required |
| Box 5 | Whether the borrower was personally liable for repayment of the debt |
| Box 6 | Description of the secured property |
| Account number | Required when the filer has multiple accounts for the same borrower and files more than one Form 1099-A |
The amounts and dates should reflect the applicable reporting event.
For real property, Box 6 generally requires the property’s address. If the address does not adequately identify the property, additional identifying details may be necessary.
Review the official Form 1099-A instructions before entering the information.
When Is Form 1099-A Due for 2026?
Form 1099-A is generally filed during the calendar year following the qualifying acquisition or abandonment event. For events occurring during calendar year 2026, the standard filing deadlines fall in 2027.
| Filing requirement | Standard deadline | Standard deadline |
| Paper filing with the IRS | February 28, 2027 | March 1, 2027 |
| Electronic filing with the IRS | March 31, 2027 | March 31, 2027 |
| Furnishing the borrower’s statement | January 31, 2027 | February 1, 2027 |
The paper filing deadline and borrower statement deadline move to the next business day because January 31 and February 28, 2027, fall on Sundays. The electronic filing deadline remains March 31, 2027.
These dates reflect the standard federal filing schedule. Special circumstances, IRS relief, or updated instructions may affect individual filing obligations.
Lenders should also review the applicable electronic filing requirements. Under the IRS general rules, filers who are required to submit at least 10 information returns in aggregate generally must e-file, subject to applicable exceptions and waivers.
How to E-File Form 1099-A Online
Form1099Online offers an online filing option for preparing and submitting Form 1099-A. Follow these general steps to prepare the information return.
1. Access the Online Filing Service
Visit Form1099Online and create an account or sign in to an existing account.
2. Select Form 1099-A
Choose Form 1099-A, Acquisition or Abandonment of Secured Property, from the available information returns and select the applicable tax year.
3. Enter Lender and Borrower Information
Provide the required identifying details for the lender and borrower. Enter the applicable TINs, mailing addresses, and account number when required.
4. Provide Debt and Property Details
Enter the acquisition or abandonment date, outstanding principal balance, applicable fair market value, borrower liability information, and property description.
5. Review the Completed Form
Check the names, TINs, dates, amounts, and property details before submission. Correct any inaccurate or incomplete information.
6. Submit and Check Filing Status
Follow the platform’s submission instructions and review any applicable service charges. After submitting the return, check the available filing status and address any rejection notices or corrections that may arise.
7. Furnish the Borrower’s Statement
Provide the borrower with Form 1099-A or an acceptable substitute statement by the applicable deadline. Keep the relevant filing records for future reference.
Form 1099-A vs. Form 1099-C
Forms 1099-A and 1099-C both relate to secured property and debt, but they serve different reporting purposes.
| Form 1099-A | Form 1099-C |
| Reports the acquisition or abandonment of secured property | Reports qualifying cancellation of debt |
| Includes the outstanding principal balance and property information | Includes the amount of canceled debt and other required information |
| Generally applies when the lender acquires an interest in secured property or knows of its abandonment | Generally applies when an applicable financial entity cancels $600 or more of debt and a reportable event occurs |
| Helps document information relevant to the secured property event | Reports qualifying debt cancellation to the IRS and the debtor |
For example, a lender that acquires a property through foreclosure may have a Form 1099-A reporting obligation. If the lender also cancels $600 or more of the debt during the same calendar year in connection with that foreclosure or abandonment, the IRS coordination rules may allow the lender to file Form 1099-C alone, completing the required property information in the applicable boxes.
The lender should review the current instructions to determine which form or forms are required for the specific event.
Frequently Asked Questions
What is Form 1099-A used for?
Who is required to file Form 1099-A?
What is Form 1099-A used for?
Who is required to file Form 1099-A?
When is the deadline to file Form 1099-A for 2026?
What is the difference between Form 1099-A and Form 1099-C?
What information is needed to complete Form 1099-A?
Can Form 1099-A be filed online?
Prepare and E-File Form 1099-A Online
Form1099Online offers an online option for preparing and submitting Form 1099-A. Before filing for calendar year 2026, gather the relevant loan and property records, verify the borrower’s information, and review the applicable IRS reporting requirements and 2027 deadlines.
Small disclaimer box text [This page provides general information about Form 1099-A for calendar year 2026, with filing generally taking place in 2027. It is not a substitute for individualized tax or legal advice. IRS forms, deadlines, and reporting requirements may change. Refer to the latest official IRS instructions for your filing situation.]